Disability insurance
Your ability to earn an income is your most valuable asset. This insurance protects it.
In brief
Disability insurance
We insure our house, our car, our phone. Yet what pays for everything else is our income. A back injury, a depression, a cancer: a six-month absence is enough to drain a family's savings. Disability insurance replaces part of that income while you recover.
How it works
If an illness or accident leaves you unable to work, as defined in the policy, and once the waiting period has passed, the insurer pays you a monthly benefit. It continues until you return to work or until the end of the benefit period.
The insurable amount is a percentage of your income, set by the insurer, so that the benefit does not exceed what you were earning. The definition of disability is the heart of the contract: inability to perform your own occupation, or any reasonable occupation given your training.
The advantages
Your budget holds up
The mortgage, the groceries and the children's education keep getting paid.
Benefits often not taxable
When you pay the premiums of an individual policy yourself.
Coverage that follows you
Unlike group insurance, it does not depend on your employer.
Options built for the self-employed
Who often have no other income protection.
Who is it for?
- Self-employed workers and entrepreneurs
- No group insurance, no bank of sick days: without income, everything stops.
- Professionals
- Doctors, dentists, engineers, accountants: the own-occupation definition protects the specialty.
- Tradespeople
- Electricians, plumbers, mechanics: an accident can keep you off work for months.
- Under-covered employees
- Those whose group coverage is capped, taxable or non-existent.
A real-life example
Simon, 38, a self-employed electrician, earns about $85,000 a year. A fall on a job site fractures his shoulder: eight months off work.
Without coverage, he would have dipped into his savings and then his line of credit. With an individual policy and a 30-day waiting period, he received a non-taxable monthly benefit from the second month until he went back to work. His family kept its standard of living.
The options available
| Waiting period | 30, 60, 90 or 120 days: choose it according to your savings cushion. |
|---|---|
| Benefits to age 65 | The best protection against a long disability. |
| Cost-of-living adjustment | So the benefit keeps up with inflation during a prolonged disability. |
| Business overhead expense | For entrepreneurs: pays rent, salaries and fixed business costs during the absence. |
| Future insurability option | To increase coverage later, as income rises, with no new medical evidence. |
Key terms
| Waiting period | The number of days of disability before the first payment. The longer it is, the lower the premium. |
|---|---|
| Benefit period | The maximum length of payments: 2 years, 5 years or to age 65. |
| Own occupation | You are considered disabled if you can no longer perform your occupation, even if you could do another. |
| Any occupation | You are disabled only if you cannot perform any reasonable job given your training and experience. |
| Partial or residual disability | A reduced benefit if you return to work part-time or with a loss of income. |
What to watch for
- The definition of disability: it determines whether you will be paid. Read it carefully.
- Exclusions and declared pre-existing conditions.
- Coordination with the SAAQ, the CNESST or group insurance: some benefits reduce one another.
- Declared income: it must be documented, especially for the self-employed.
The right questions to ask
- How many months could I last without income?
- Which definition of disability really protects me?
- Is my group coverage taxable, and is it enough?
- Do I need business overhead expense coverage?
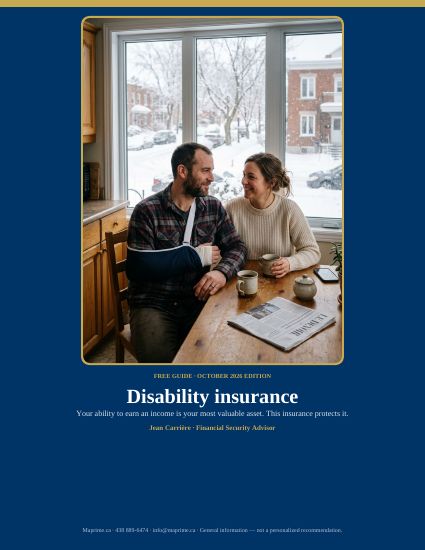
The complete guide, free
Everything you need to know, illustrated and explained in plain language, with a worked example and the pitfalls to avoid. No sign-up or email required.
Let's talk about your situation
A 30-minute meeting, in person in Montreal, by Google Meet or by phone. I compare the products of several insurers, at no cost and with no obligation.
Other protections
Sources :
- Canada Revenue Agency, tax treatment of disability insurance benefits
- Standard contracts of Canadian insurers, reviewed in October 2026
General information: this content is not personalized advice. Guarantees, exclusions and premiums are those of the insurer's contract. Images: Pexels photographs (Pexels licence) and illustrations generated by artificial intelligence; the people shown are models or fictional characters.