Montréal, Quebec
Group insurance — Québec SMEs

Group insurance and retirement savings for your business

A protected team is a team that stays. Group insurance and retirement savings for Québec SMEs, compared across several insurers.

No personal information is requested before the end of the questionnaire. Both tools give a general picture: they do not replace a review of your contract, whose coverages, exclusions and conditions prevail.

By industry

A group plan designed for your industry

Choose your industry: the risks, the priority coverages and a practical tip for each.

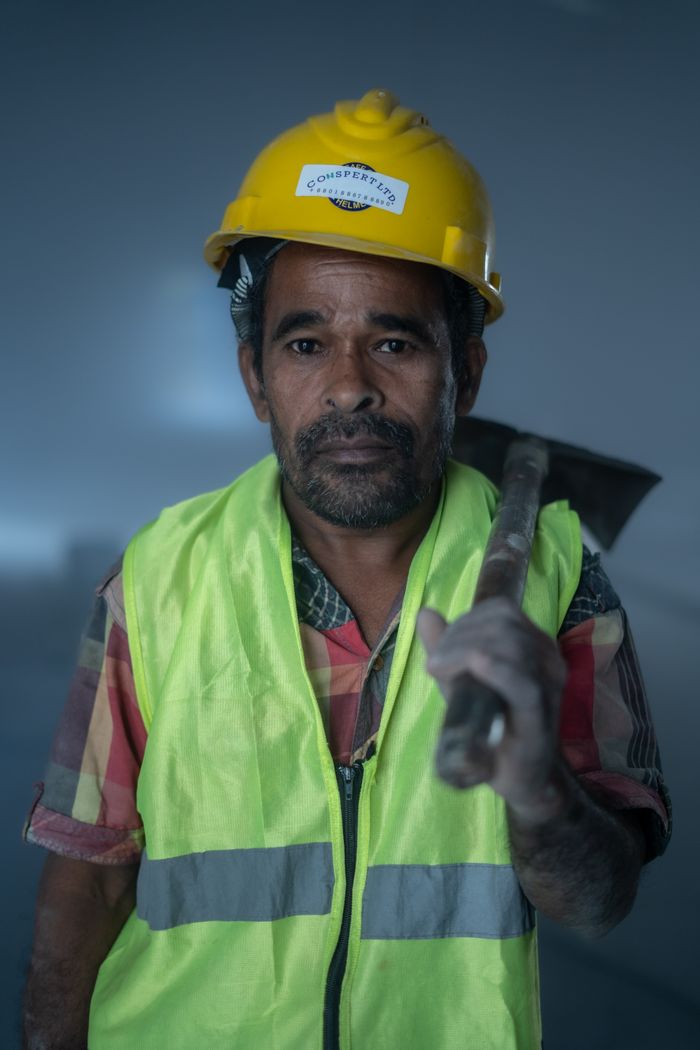
Construction crew on a job site

Construction and trades

Employees covered by the construction industry collective agreements already have the MÉDIC Construction plan administered by the Commission de la construction du Québec (CCQ). Office staff, estimators and managers do not.

Priority coverages

  • Life and accidental death and dismemberment
  • Short- and long-term disability
  • Health and drug coverage for non-CCQ staff

Tip Separate CCQ-covered positions from the others before requesting a quote: it avoids paying twice for the same protection.

Quote for this industry →
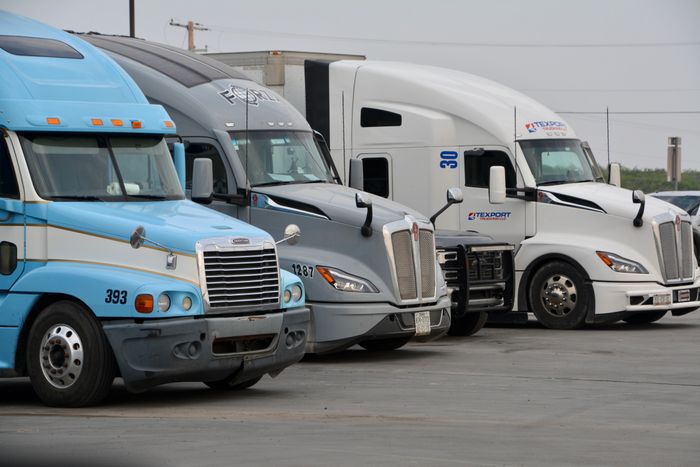
Heavy trucks parked in a transport yard

Transportation and logistics

Irregular hours, long absences, medical requirements tied to the driver's licence: a disability can take a driver off the road for months.

Priority coverages

  • Long-term disability with an occupation-specific definition
  • Telemedicine available on the road
  • Travel insurance for trips outside Québec

Tip Check the disability definition: "unable to perform their own occupation" protects a driver better than "any occupation". See also our transportation and aviation page. Transportation and aviation page →

Quote for this industry →
Factory worker in protective equipment

Manufacturing and warehousing

The CNESST compensates employment injuries, but not an illness or accident that happens outside work. That is where group disability coverage takes over.

Priority coverages

  • Short-term disability to complement Employment Insurance
  • Employee Assistance Program (EAP)
  • Paramedical care: physiotherapy, massage therapy

Tip A qualifying short-term disability plan can reduce your employer Employment Insurance premiums through the Premium Reduction Program.

Quote for this industry →
Chef plating a dish in a kitchen

Restaurants and hospitality

High turnover, part-time work, young workers: the plan must stay simple and affordable while helping you keep your best people.

Priority coverages

  • Adapted waiting period for eligibility (for example 3 months)
  • Minimum hours threshold for part-time staff
  • Telemedicine and EAP, highly valued and inexpensive

Tip A modular plan (mandatory core, optional modules) controls costs while offering a real hiring advantage.

Quote for this industry →
Nurse with a patient in a clinic

Clinics, pharmacies and health care

Incorporated professionals and their staff have different needs: separate classes within the same plan are often required.

Priority coverages

  • Employee classes (professionals, support staff)
  • Disability with own-occupation protection
  • Health care spending account for flexibility

Tip Incorporated professionals should check how the group plan interacts with their individual coverage to avoid duplication.

Quote for this industry →
Smiling employee in a retail store

Retail

Several locations, variable schedules and often young staff: easy enrolment and digital access make the difference.

Priority coverages

  • Online enrolment and claims
  • Basic dental care
  • Group retirement savings (VRSP or group RRSP)

Tip With 5 or more eligible employees, a business must offer a VRSP unless it already offers another qualifying plan. A group RRSP with payroll deduction can take its place.

Quote for this industry →
Diverse team meeting in an office

Offices, professional services and tech

Competition for talent is strong: the quality of the plan weighs in a candidate's decision.

Priority coverages

  • Health care spending account and wellness account
  • Enhanced life and disability insurance
  • Group RRSP or DPSP with employer contributions

Tip Show the plan in dollars in your job offers: the annual value of the coverages makes total compensation more visible.

Quote for this industry →
Mechanic at work in a garage

Garages and automotive services

Physical work and small teams: an injury outside work can halt the shop and the technician's income.

Priority coverages

  • Short- and long-term disability
  • Paramedical care and physiotherapy
  • Life and critical illness insurance

Tip Small teams are often eligible for a group plan from just a few employees, depending on the insurer: age and group size are not an obstacle.

Quote for this industry →
Educator surrounded by children in a child care centre

Child care, education and non-profits

Tight budgets and a social mission: every dollar must count, but staff retention is crucial.

Priority coverages

  • Core plan shared by employer and employees
  • EAP to help prevent burnout
  • VRSP with no mandatory employer contribution

Tip Premium sharing can be set per coverage: an employee who pays their own disability premium receives non-taxable benefits.

Quote for this industry →
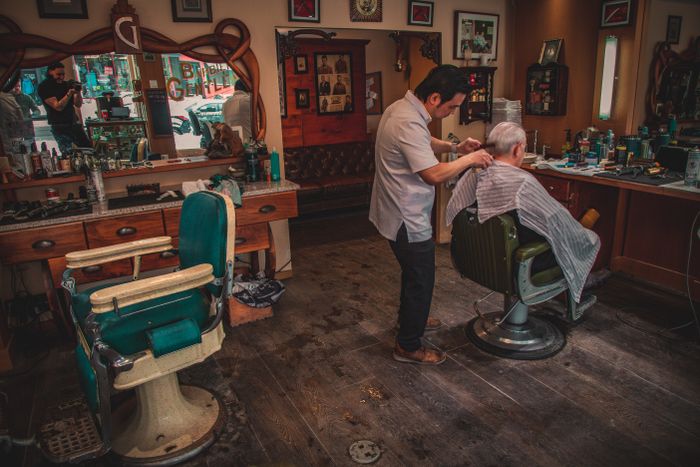
Barber cutting a client's hair in his shop

Hair, beauty and personal care

Often very small teams, sometimes self-employed workers: there are solutions designed for small groups.

Priority coverages

  • Health and drug coverage
  • Disability coverage suited to standing work
  • Basic life insurance

Tip If your collaborators are self-employed, they are not eligible for the employee plan: individual coverage is then the right path.

Quote for this industry →

Coverages, tips and guide

Each coverage explained simply

What each product covers, the tip that changes the bill or the net income, and the points to check in your contract.

01Group life insurance and AD&D

A lump sum paid to the beneficiaries when the employee dies, often a multiple of salary (for example 1 or 2 times), with accidental death and dismemberment (AD&D) coverage.

Tip Employer-paid life insurance premiums are a taxable benefit for the employee. Coverage ends when the employee leaves the company: the right to convert to an individual policy must usually be exercised within a short period, often 31 days.

Guide: points to check in your contract

  1. Compare the amount with the family's real needs (mortgage, income, education)
  2. Review designated beneficiaries after every life change
  3. Add a personal policy that follows the employee
02Short-term disability

Replaces part of the salary during the first weeks of an absence due to illness or accident, in addition to or instead of Employment Insurance sickness benefits (up to 26 weeks).

Tip A qualifying plan may entitle the employer to a reduced Employment Insurance premium rate. The waiting period and the maximum duration determine the cost.

Guide: points to check in your contract

  1. Choose the waiting period (accident and illness)
  2. Coordinate the duration with the start of long-term disability
  3. Assess the Employment Insurance premium reduction
03Long-term disability

Pays a monthly benefit, often 60% to 70% of salary, after the waiting period (frequently 17 or 26 weeks) and for the duration of the disability, sometimes up to age 65.

Tip If the employee pays the entire premium, the benefits received are not taxable. If the employer pays, they are taxable: premium sharing changes net income in case of disability.

Guide: points to check in your contract

  1. Read the definition of disability (own occupation or any occupation)
  2. Check the monthly maximum against higher salaries
  3. Have the employee pay the premium where possible
04Health and drug coverage

Reimburses prescription drugs, paramedical care (physiotherapy, psychology, massage therapy), hospital expenses and vision care.

Tip In Québec, a person eligible for a group plan that includes drug insurance must join it, and enrol their spouse and children if they are not covered elsewhere. The share of the premium paid by the employer is a taxable benefit for provincial tax purposes.

Guide: points to check in your contract

  1. Choose the coinsurance and deductible
  2. Check pooling for high-cost drugs
  3. Add telemedicine and online pharmacy
05Soins dentaires

Covers preventive care, restorations and, depending on the plan, major services and orthodontics.

Tip The Canadian Dental Care Plan is for people without access to dental insurance: an employee covered by the group plan is generally not eligible.

Guide: points to check in your contract

  1. Cap major services and orthodontics to control costs
  2. Set the fee guide used (current or previous year)
  3. Provide a waiting period for major services
06Group critical illness

A lump sum paid on diagnosis of a covered illness (cancer, heart attack, stroke, etc.).

Tip The amount can be used freely: treatments, home adaptation or replacing a spouse's income.

Guide: points to check in your contract

  1. Compare the list of covered illnesses
  2. Check coverage for children
  3. Offer an optional, employee-paid module
07Employee Assistance Program and telemedicine

Confidential access to psychological, legal or financial counselling, and to a doctor online.

Tip These are often the most used and least expensive coverages: they reduce absenteeism related to mental health.

Guide: points to check in your contract

  1. Promote the EAP from the onboarding of new employees
  2. Check the number of sessions included
  3. Measure usage at each renewal
08Health care spending account and wellness account

A fixed annual amount the employee uses for health expenses not otherwise covered or, for a wellness account, for wellness activities.

Tip The cost is known in advance. In Québec, health care spending account amounts paid by the employer are taxable provincially; the wellness account is taxable at both levels.

Guide: points to check in your contract

  1. Set an amount per employee class
  2. Allow unused balances to be carried forward
  3. Use it to complement a core plan
09Group travel insurance

Covers emergency medical expenses outside the province and, depending on the contract, trip cancellation.

Tip Useful for employees who travel for work or on vacation: hospital costs abroad can be very high.

Guide: points to check in your contract

  1. Check the maximum duration per trip
  2. Confirm 24/7 assistance
  3. Read the exclusions for pre-existing conditions

General information. The coverages, exclusions and conditions of your contract prevail.

Group retirement savings

VRSP, group RRSP, DPSP, TFSA: which one to choose?

VRSP

Voluntary Retirement Savings Plan (RVER). Mandatory in Québec for an employer with at least 5 eligible employees (18 or older, at least one year of continuous service) that does not already offer a qualifying plan. Employee contribution of 4% by default; the employer contribution is optional.

Group RRSP

Contributions deducted from pay immediately reduce the income tax withheld at source. Employer contributions are subject to payroll taxes.

DPSP

Deferred Profit Sharing Plan: funded only by the employer, often paired with a group RRSP. Employer contributions are not subject to payroll taxes such as QPP or Employment Insurance.

Group TFSA

Tax-free savings when withdrawn, flexible for short- and medium-term projects. Contributions are not deductible from income.

Tip A group RRSP with payroll deduction exempts the employer from offering a VRSP. Paired with a DPSP, it allows an employer contribution without payroll taxes on the DPSP portion.

Free guide

The group insurance guide, to print or download

All coverages, tips and points to check, industry by industry, in a clear PDF to share with your committee or accountant.

FAQ

Group insurance: your questions

How many employees does a business need to offer group insurance?

Several insurers accept small groups from just a few employees; conditions (evidence of insurability, available coverages) vary by insurer and group size. A comparative quote shows the real options for your business.

Is group insurance mandatory in Québec?

No, employers are not required to offer group insurance. However, an employer with at least 5 eligible employees must offer a VRSP if it does not already offer a qualifying retirement savings plan. And an employee eligible for a group plan that includes drug insurance must join it.

Who pays the premium: the employer or the employee?

The split is flexible and can vary from one coverage to another. A common practice is to have employees pay for long-term disability so that benefits are non-taxable, and to have the employer pay all or part of the other coverages.

What happens to my coverage if I leave my job?

It generally ends when employment ends. Some coverages, such as life insurance, can be converted to an individual policy without evidence of insurability if the request is made within the period set out in the contract, often 31 days.

How often should a plan be compared?

The plan is renewed every year, but a full marketing every three to five years is a common practice to make sure the premium and coverages remain competitive.

How long does it take to set up a plan?

It generally takes a few weeks between gathering information, comparing quotes, choosing the plan and enrolling employees.

Ready to compare your plan or create one?

Get a group insurance quote Book an appointment
Group insurance at a glance
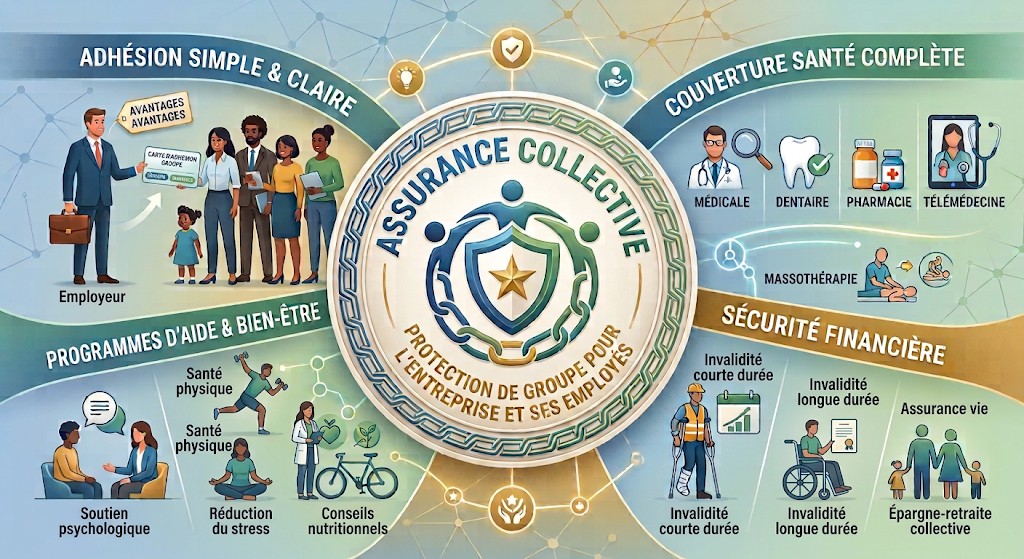
Group insurance: simple enrolment, comprehensive health coverage (medical, dental, pharmacy, virtual health, paramedical care), assistance and wellness programs, and financial security (short- and long-term disability, life insurance).

Our other coverage

Term life insurance

The most protection for the lowest cost

Coverage for 10, 20 or 30 years, at the lowest cost per dollar of coverage, for the years your family depends on you: mortgage, children, debts. It can usually be converted later to permanent insurance without new proof of health.

Our partners

  • iA Groupe financier
  • Manuvie
  • Canada Vie
  • Empire Vie
  • Sun Life
  • Beneva
Get a quote

An advisor will reply, free and without obligation.
Group insurance and annuities

Offer more to your team

Group insurance (life, disability, health and dental) and group retirement savings (group RRSP, VRSP, DPSP). A well-designed plan helps attract and keep employees, and employer contributions are generally deductible.

Our partners

  • Canada Vie
  • Sun Life
  • Manuvie
  • Manulife Bank
  • Desjardins
  • iA Groupe financier
Get a quote

An advisor will reply, free and without obligation.
Insurance with cash value

Protection that grows in value

Whole life insurance protects your family for life and builds a guaranteed cash surrender value. Participating policies may also pay annual dividends, which are not guaranteed.

Our partners

  • Sun Life
  • Canada Vie
  • Équitable
  • iA Groupe financier
Get a quote

An advisor will reply, free and without obligation.
Universal life insurance

Protection and savings, with flexibility

Universal life separates the cost of coverage from the savings component, which grows tax-sheltered within permitted limits. You adjust deposits to your budget and choose your investment options.

Our partners

  • Manuvie
  • Manulife Bank
  • Desjardins
  • ivari
  • iA Groupe financier
  • Équitable
Get a quote

An advisor will reply, free and without obligation.
Mortgage insurance

Protect your home and your family

Individual mortgage insurance belongs to you: the benefit is paid to your beneficiaries, who decide how to use it, and the coverage follows you if you change lenders. Compare it with the bank's offer before you sign.

Our partners

  • Beneva
  • Humania Assurance
  • UV Assurance
Get a quote

An advisor will reply, free and without obligation.
You are…

Choose your situation: I'll show you what matters, straight to the point.

Is your group plan up to par?

I compare plans from several insurers for SMEs and their employees, at no cost and with no obligation.